Far East Hospitality Trust Q3 Income Rises as Japan Hotels Lift Revenue
Far East Hospitality Trust’s Q3 income available for distribution rose 6.3% to S$20.2 million, with Japan hotel revenue offsetting softer Singapore tourism demand.
Far East Hospitality Trust’s third-quarter results show how a strong contribution from one Japanese hotel can lift portfolio income even as Singapore tourism demand remains subdued. Net property income rose 6.3 per cent year on year to S$27.6 million, while income available for distribution increased by the same rate to S$20.2 million. The parallel gains suggest that higher property income flowed through to distributions during the quarter, with lower finance expenses providing additional support. But the headline growth rate masks a clear difference between the trust’s markets: Japan surged from a smaller base, while Singapore, the larger hotel contributor, barely grew.
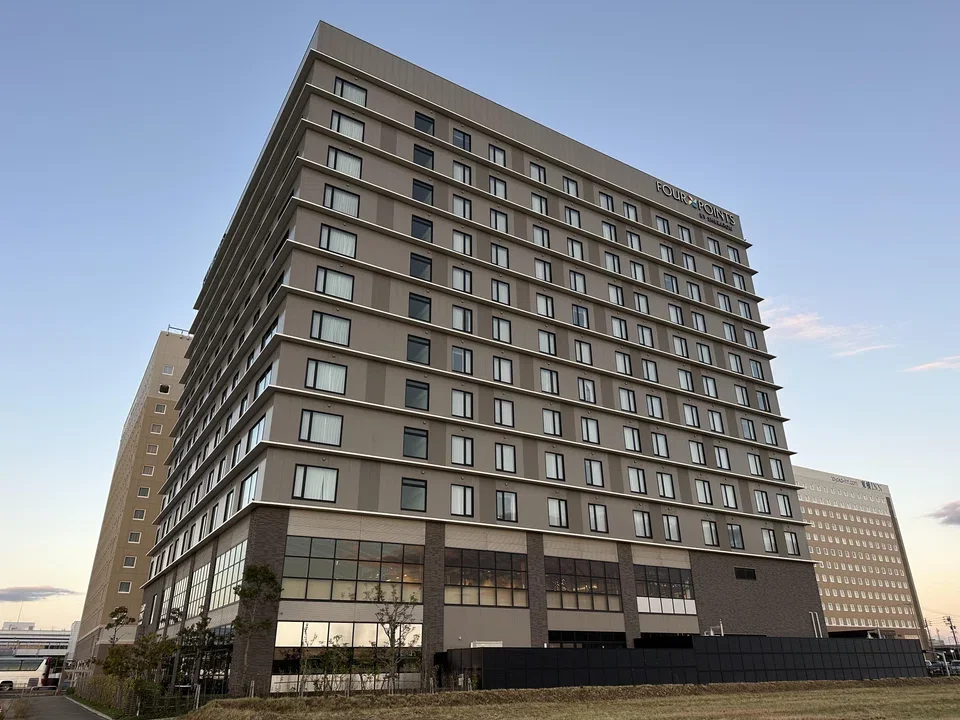
Gross revenue for the quarter reached S$32.6 million, up 7.2 per cent from S$30.4 million in Q3 2025. The main driver was Four Points by Sheraton Nagoya, where demand associated with the Asian Games 2026 supported a stronger showing. The hotel was contracted for the event, giving the Japan portfolio a lift that was visible across several operating measures. That link matters when reading the result: event-related demand can move a hotel’s quarterly figures sharply, while offering less certainty about the pace of performance in periods without a comparable catalyst.
Japan drives hotel growth
Revenue from FEHT’s hotel portfolio rose 9.2 per cent to S$25 million from S$22.9 million. Within that result, Japanese hotel revenue climbed 71.7 per cent to S$4.6 million, compared with S$2.7 million in the year-ago quarter. Revenue per available room for the Japanese portfolio increased 48.7 per cent to 12,502 yen (US$79), from 8,409 yen. The gains in both revenue and revenue per available room point to a stronger operating quarter, though the figures alone don’t show how much came from event demand versus other sources.

Those figures point to a sharp improvement in Japan, but the scale of the contribution matters: the portfolio’s Japanese hotel revenue was S$4.6 million, while its Singapore hotels generated S$20.4 million. The quarter’s overall hotel growth therefore combined a pronounced gain in Japan with a much steadier result at home. Japan’s percentage increase is striking; its absolute contribution remains smaller, which limits how far that growth can offset weakness elsewhere in the portfolio.
Singapore hotel revenue edged up 0.9 per cent to S$20.4 million from S$20.2 million. Revenue per available room held at S$148, unchanged from a year earlier. FEHT’s managers said visitor arrivals in Singapore fell 1.8 per cent year on year in Q3 2026, while visitor days declined 5.1 per cent. That softness helps explain why room revenue grew only modestly despite the broader increase in group revenue. A stable revenue per available room can indicate that pricing held up, but it doesn’t erase the weaker visitor-day trend or show whether demand will strengthen in a later quarter.
Other assets and financing
The serviced residence portfolio contributed S$3 million in Q3 revenue, 5 per cent more than the S$2.9 million recorded in the corresponding period a year earlier. Commercial premises and other income moved in the opposite direction, slipping 1.2 per cent to S$4.5 million from S$4.6 million. These changes were smaller than the swings in Japanese hotel revenue, but they show that the quarter’s growth wasn’t uniform across the trust’s operating segments. For investors assessing the quality of revenue growth, the distinction between hotel room demand and income from other assets is useful.
Financing costs provided another source of support. Finance expenses fell 16 per cent year on year, mainly because the average cost of debt was lower. As at Sep 30, that cost stood at 2.3 per cent, down from 3.2 per cent a year earlier. Together with higher net property income, the reduction in finance expenses helped take income available for distribution to S$20.2 million from S$19 million. That’s a meaningful contribution to distribution growth: operating revenue matters, but so does the share of it left after paying to finance the portfolio.
FEHT reported aggregate leverage of 33.2 per cent at the end of September and total debt of S$781.5 million. The lower borrowing cost improved the period’s distribution income, though the debt balance and future financing costs remain relevant to how much of the property income reaches investors. The cost reported for the period is a snapshot; it doesn’t establish that the same level will persist. And this is the part most people overlook: a favorable financing contribution can lift current results even when underlying room demand is uneven.
Events offer a demand catalyst
The managers expect the portfolio to benefit from business travel and from meetings, incentives, conferences and exhibitions, as well as events. They pointed to the recently concluded Formula 1 Singapore Grand Prix and the BTS world tour scheduled for December as examples of activity that could support hotel demand. Such events can bring concentrated bursts of visitors, which may help room revenue in the periods when they take place. The size and duration of that benefit, however, will depend on actual bookings and how broadly demand reaches across the portfolio.
That outlook sits alongside the quarter’s mixed operating picture: event-related demand helped lift Nagoya, while Singapore hotel revenue was nearly flat and visitor days declined. The results show the value of having properties exposed to different sources of travel demand, but also how a standout event can shape comparisons for an individual quarter. This is more significant than it looks: the trust’s growth rate depends not only on whether travel demand improves, but on where that demand lands and whether it persists beyond a specific event.
What to watch in the next period
FEHT stapled securities closed on Wednesday at S$0.50, up 1 per cent, or S$0.005. That single-session move offers little evidence by itself about how investors will weigh the quarter’s uneven operating trends. If you’re working in this space, the more useful signals are whether Japanese hotel performance can sustain its elevated contribution, whether Singapore room demand firms, and whether the lower average cost of debt continues to ease finance expenses.
For now, the distribution increase has support from both higher net property income and cheaper debt, while the largest hotel market delivered only modest revenue growth. The next period will help show whether the Japanese result reflects a wider improvement in demand or a temporary event-led lift. A steadier Singapore contribution would also matter, given its larger share of hotel revenue. For the quarter reported, the growth is real, but its sources are uneven.


