UltraGreen.ai Revenue Rises 43.9% as US Competition Puts FY2026 Target Out of Reach
UltraGreen.ai posted US$44.6 million in Q3 revenue but expects FY2026 to miss guidance as new US competitors pressure pricing and purchasing.
UltraGreen.ai’s revenue grew strongly in the third quarter, but the company now expects full-year revenue to fall below its earlier target. The gap between those two signals reflects a changing US market: competing indocyanine green (ICG) products are pressuring prices and altering customer purchasing patterns, and the company expects the impact to extend into FY2027.
Revenue for Q3 2026 rose 43.9 per cent to US$44.6 million from US$31 million in Q3 2025. For the nine months ended Sep 30, revenue increased 35 per cent to US$131.8 million from US$97.6 million a year earlier. Those growth rates show expansion across the business, while the revised outlook points to mounting pressure on the company’s ability to sustain that pace.
US growth meets a tougher market
The US remains UltraGreen.ai’s largest source of revenue. Sales there climbed 47 per cent to US$35.2 million in Q3 2026 from US$23.9 million in the year-earlier quarter. For the first nine months, US revenue rose 35 per cent to US$101.3 million from US$75.2 million.
Revenue from the rest of the world also advanced. It increased 32 per cent to US$9.4 million in Q3 from US$7.1 million, and grew 36 per cent to US$30.5 million in the nine-month period from US$22.5 million. The figures show that growth is not confined to the US, though the US still accounts for the larger share of reported revenue.
The company says the US operating environment has become less predictable since competing ICG products entered the market. Zydus and Provepharm have received approval to produce and sell ICG products in the US. UltraGreen.ai says the new competition is contributing to pricing pressure and shifts in how customers buy.
That matters because rising revenue alone doesn’t reveal how much volume growth, pricing, or customer mix is contributing to the result. The company did not provide a breakdown of those factors in the figures reported here. With new products affecting the market, maintaining revenue growth may depend on how customers respond to competing options as well as on UltraGreen.ai’s ability to retain distribution and demand.

Outlook and commercial response
UltraGreen.ai expects FY2026 revenue to be below its earlier guidance of US$175 million to US$185 million. It also expects the competitive impact to continue into FY2027, making the pressure more than a single-quarter issue. The company has not given a replacement full-year target in the information reported here.
CEO Ravinder Sajwan said the company is engaging more closely with customers and distribution partners, broadening its commercial offering and managing costs. UltraGreen.ai has relaunched its own generic ICG product through US partners, giving customers a competitively priced option alongside its branded product. The company is also working with channel and distribution partners to preserve market access and track changes in customer purchasing and adoption of competing products.
Its response also includes efforts to expand sales beyond the existing ICG offering. Sajwan said UltraGreen.ai is accelerating the commercial rollout of its imaging systems and developing opportunities in additional clinical settings, including outpatient care and wound management. The company also plans to strengthen its presence outside the US. These efforts could broaden its sources of demand, but the information provided does not quantify their expected contribution to revenue.
Cost control is another part of the response. UltraGreen.ai says it is reviewing operational efficiency and its cost structure to support profitability in a changing market. The reported revenue figures do not include enough information to assess how pricing pressure or the cost measures are affecting margins.
Capital returns and international reach
The board has approved a capital allocation framework that places reinvestment in the business first, followed by sustainable dividends, strategic acquisitions and share buybacks. The annual dividend target is at least 30 per cent of earnings excluding exceptional items, with distributions planned twice a year. Any payment will depend on earnings, cash flow and capital requirements and remains subject to board approval.
UltraGreen.ai also announced a multi-year share buyback programme of up to US$30 million. Buybacks will be carried out opportunistically, taking account of the company’s capital priorities, market conditions, valuation and liquidity. The programme sets a maximum amount; it does not establish how much the company will spend or when it will buy shares.
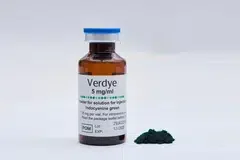
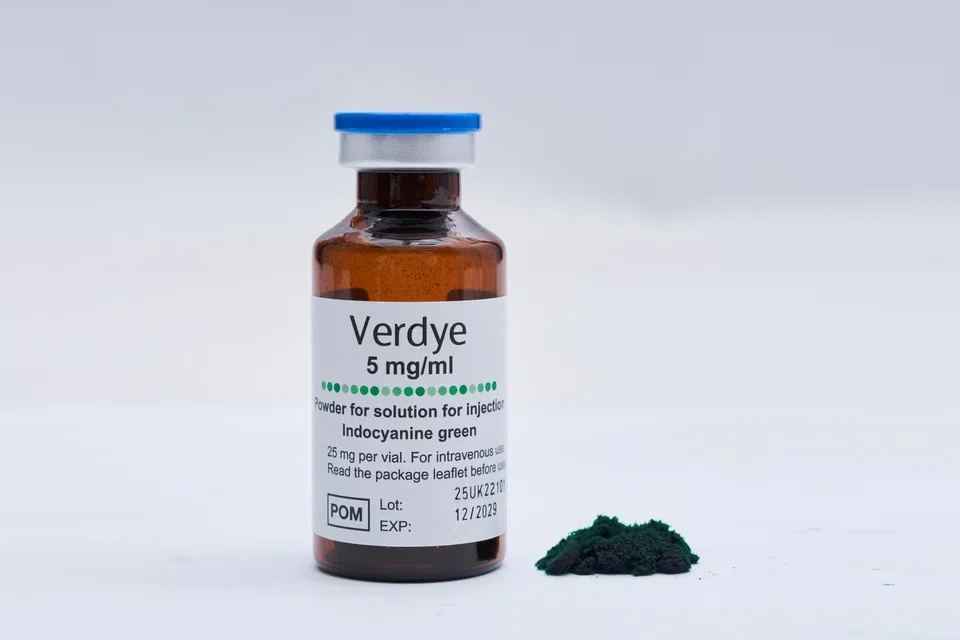
Outside the US, UltraGreen.ai received European MDR CE certification for PerfusionWorks, its tissue perfusion analysis software, and approval for Verdye ICG in South Africa. The company says the South African approval brings its presence to 42 countries. These developments add to its international footprint as it seeks to build growth outside its most competitive market.
UltraGreen.ai shares closed up 7.6 per cent, or US$0.04, at US$0.565 on Wednesday. The next measures to watch are whether the company can sustain growth amid US pricing pressure, how its broader product and geographic push develops, and whether its cost actions support profitability while it funds dividends and potential buybacks.


