Mi Material posts US$11.4 million Q3 adjusted profit as nine-month revenue reaches US$91.5 million
Mi Material’s nine-month adjusted profit exceeded its FY2025 total, while the company expects Q4 revenue to top Q3 on seasonal demand.
Earnings have moved ahead of last year
Mi Material’s first nine months of 2026 have already outpaced its full-year 2025 adjusted profit, giving the newly listed semiconductor materials maker a stronger earnings base as it heads into its traditionally busiest quarter. The company reported adjusted profit after tax of US$11.4 million for the third quarter ended Sep 30 and US$25.7 million for the nine months. That nine-month result is more than twice the US$10.5 million recorded for all of FY2025, though a nine-month comparison with a full year can’t establish where 2026 will end.
Third-quarter revenue was US$37.8 million, up 15.6 per cent from US$32.7 million in the preceding quarter. For the first nine months, revenue reached US$91.5 million, already above the full-year totals reported for FY2025, FY2024 and FY2023. Those figures were US$65.3 million, US$46.8 million and US$39.8 million, respectively. The scale of the increase is clear; what’s less clear from the update is how much came from higher volume, higher prices or a change in the products sold.
Demand and pricing supported growth
Mi Material attributed the nine-month revenue increase to higher sales volume and average selling prices. It said demand for its proprietary patented alloy solder spheres remained strong among customers serving high-performance computing and memory, as well as mobility and wearables. Both volume and pricing contributed, but the company didn’t quantify their separate effects. That leaves readers without a detailed view of which factor did more to lift revenue.
The mix matters because those end markets use advanced packaging materials in different ways. High-performance computing and memory demand is tied to increasingly capable semiconductor systems, while premium mobile and wearable devices call for smaller components and more connections within limited space. Mi Material pointed to miniaturisation and higher input/output density in premium devices as support for demand in the latter segments. Similar materials businesses can serve more than one application, but the demands of each market may differ in product specifications and customer needs.
That breadth may help explain why the company is seeing demand across several semiconductor-related markets, though the update doesn’t disclose how sales are split among them. A broad set of end markets can provide more than one source of demand; it can also make product mix harder to assess from headline revenue alone. If you’re working in this space, the distinction matters: growth in total sales doesn’t by itself show which applications are driving the strongest or most durable returns.
The company said sustained demand for semiconductor packaging materials also supported its improved profitability. Its adjusted profit after tax for the first nine months of 2026 was more than twice the US$10.5 million recorded for the whole of FY2025. This is more significant than it looks at first glance, because the nine-month figure already exceeds the prior full-year result. Still, it’s an incomplete comparison: the reporting periods differ, and the figures don’t tell us whether the recent profit level can be maintained.
Q4 outlook rests on seasonal strength
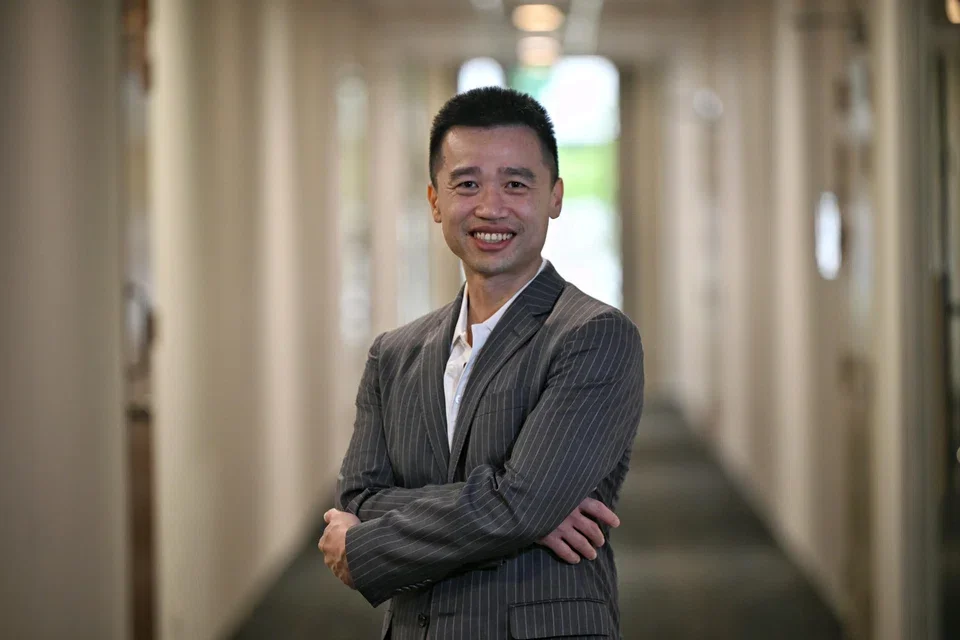
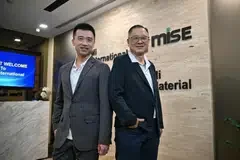
Mi Material expects Q4 revenue to exceed Q3, citing historical trends. Chief executive and executive director Kevin Tan described the coming period as the company’s traditionally strongest quarter and said it was optimistic about the opportunities ahead. That expectation gives the company a clear near-term benchmark, but the update doesn’t provide a revenue target or a range for the quarter. Seasonal strength is part of the company’s case; the result will depend on how demand and production develop in practice.
That expectation puts execution at the centre of the near-term outlook. Mi Material said it plans to optimise production schedules and order allocation to serve peak Q4 demand. The company also identified maintaining raw material passthrough as a priority for protecting gross profit margins. If costs change, the pace and extent to which they can be passed through to customers could affect profitability. Here’s the thing: higher revenue won’t automatically mean higher profit if the cost of materials rises faster than the company can adjust prices.

Another stated priority is to commence production in Senai, Malaysia. Tan said the company intended to expand manufacturing capacity and advance research and development initiatives. The update didn’t specify a production start date, capacity target or expected financial contribution from the Senai operation. Those details would help readers judge when the expansion might affect output and earnings, but they aren’t available in the reported information.
Capacity plans and order allocation are closely linked to the seasonal outlook. If demand reaches the level the company expects, production planning will need to match orders with available output while maintaining material supply. (And this is the part most people overlook: a strong order environment can still test a manufacturer’s ability to deliver consistently.) Execution, then. The company has identified the task, but the update offers no operational detail that would show how much additional capacity is ready for the quarter.
Newly listed shares close at IPO price
The business update came one day after Mi Material’s debut on the local mainboard. Its shares finished the first trading day at S$1.82, slightly above the S$1.80 initial public offering price. On Thursday, the counter ended at S$1.80, down 1.1 per cent, or S$0.02, before the results were announced. That sequence records a small move around the listing and results update; it doesn’t, on its own, explain how investors assess the company’s longer-term prospects.
The share-price movement provides a brief snapshot of trading around the listing, while the quarterly figures offer an early view of the company’s operating performance as a public issuer. The source figures don’t state how much of the revenue or profit growth came from each product or customer segment, so the contribution of individual markets remains unclear. That limits what can be inferred from the headline growth: strong aggregate results don’t show whether performance is evenly spread or concentrated in particular areas.
What to watch in the next quarter
For investors and industry watchers, the next evidence will come from whether the expected Q4 revenue increase translates into sustained margins and whether production planning can meet peak orders. Mi Material’s results point to expanding demand across several semiconductor-related markets; its ability to convert that demand into profitable growth will depend in part on pricing, material costs and capacity execution. The company has described its priorities, but the update doesn’t give enough detail to measure the expected contribution of each one.
That said, the nine-month figures establish a stronger earnings base than the prior full-year comparison alone might suggest. The next quarter will show whether seasonal demand lifts revenue as expected and whether the company can protect margins while serving that demand. For now, the reported growth is tangible; the durability of the improvement remains an open question.


