Michael Selig Sets CFTC Priorities for 24/7 Trading, Tokenized Collateral and AI
Selig outlined plans for derivatives markets as continuous trading, tokenized collateral, crypto products and AI challenge existing oversight and operations.
Derivatives markets are changing faster than some of the rules and operating systems built to support them. At the CFTC, Chairman Michael S. Selig says the response will involve revisiting existing requirements while working through the practical demands of continuous trading, tokenized collateral, new contract designs and artificial intelligence.
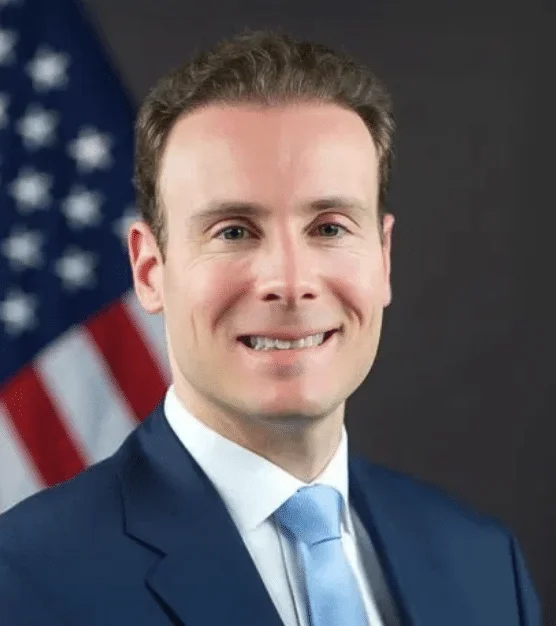
Speaking with SIFMA President and CEO Kenneth E. Bentsen, Jr. at SIFMA’s 2026 Annual Meeting on Tuesday, October 20, Selig described priorities spanning market access, oversight and the cost of serving commercial customers. His remarks point to a broad test for the agency: adapt to new products without weakening safeguards that have proved useful.
Trading hours bring different risks across markets
Continuous trading is already permitted for some products, including cryptocurrencies and certain prediction markets. Extending hours for agricultural and energy derivatives raises different operational questions, Selig said, and commercial participants have voiced concerns. The CFTC has been working with exchanges and market participants to address them. “It’s not going to be a one-size-fits-all approach for 24/7 at the CFTC,” he said.
The contrast matters because a market that remains open through nights and weekends needs people and systems ready to respond outside normal schedules. Selig cited negative oil prices during the COVID-19 pandemic as a reminder that extreme conditions can challenge firms’ ability to manage markets. He said firms should prepare for possible extended hours by considering staffing, technology and additional coverage.
Selig also pointed to CME’s withdrawal of a proposed extended-hours offering for energy products, describing the exchange as cooperative in addressing industry concerns. The agency may need additional rules or statutory changes before certain products can trade continuously. “We can only hold up these products for so long,” he said, suggesting the discussion will continue as exchanges and users weigh the benefits against operational demands.
Collateral and contract design are shifting
Tokenized assets could make it easier to move collateral when traditional banking channels are less available. That has particular relevance when positions remain open over weekends: firms may otherwise hold more collateral than they would during standard hours. “With stablecoins and other types of tokenized assets, you can freely move them just like you would during regular trading hours,” Selig said.
The CFTC is coordinating with the SEC on using tokenized securities as collateral in regulated markets. Selig also described potential uses for smart contracts, which can automate collateral movements according to programmed conditions. The agency is speaking with software developers to understand how blockchain-based systems function and whether regulatory relief may be needed. For market users, the potential gain is more flexible collateral movement and more efficient use of capital; the systems and rules still need to fit together.
Perpetual futures, which have no fixed expiration date, are another focus. Selig said existing statutes leave room for such contracts to be structured as futures or swaps, while acknowledging that some products could warrant added requirements. Renewed interest in security futures, including activity involving CME and firms seeking to list perpetual products, adds to the need for coordination between the CFTC and SEC.
The agencies are also working through product classification, cross-margining and jurisdictional questions involving derivatives and prediction markets. Selig compared the relationship between securities and derivatives oversight to a Venn diagram: depending on a product’s structure, it may fall under either framework. Greater coordination could help clarify how firms handle products that sit across those boundaries.
Crypto registration and AI surveillance
The CFTC is pursuing a federal registration route for eligible cryptocurrency exchanges under its existing authority, after broader crypto market structure legislation made little progress. The proposed approach would let firms register as designated contract markets, or under a proposed crypto asset market category. Existing designated contract markets, futures commission merchants and derivatives clearing organizations could use their established infrastructure, Selig said.
The framework would allow firms to combine activities within one business, while requiring separate registrations for brokerage, trading and clearing. But voluntary registration would leave some exchanges operating under state money transmitter frameworks. Selig argued those arrangements were designed for payment businesses rather than exchanges, and said more comprehensive legislation would offer a more durable basis for crypto market oversight.
AI presents a separate surveillance challenge as trading firms and retail participants adopt more advanced tools. Asked whether circuit breakers would remain adequate if autonomous systems contributed to market disruptions, Selig said the CFTC is monitoring AI use and assessing whether existing requirements need updating. He wants a framework that allows firms to develop trading strategies while preserving market safeguards. The agency is also building AI tools for enforcement and surveillance, alongside its continuing reliance on exchanges and the National Futures Association for market oversight.
Capital costs and access for commercial hedgers
Selig raised concerns that bank capital requirements can make derivatives market access more expensive than the risks warrant. The CFTC is engaging with other financial regulators on Basel III requirements and their effects on futures commission merchants and commercial hedgers. According to Selig, the cost has discouraged some intermediaries from serving smaller customers, including farmers, ranchers and producers. Some firms may struggle to access risk-management markets or have to post excess funds, he said.
That question connects the agency’s technology agenda to its traditional role in supporting hedging. Tokenization and round-the-clock trading may change how firms manage collateral and exposure, but access also depends on whether intermediaries can serve customers at a viable cost. Selig’s broader point was that derivatives markets have changed substantially over two decades. How the CFTC updates its rules, market systems and coordination with the SEC will shape whether new products can operate alongside the risk-management needs of commercial users.
The image for this article was generated using AI.


