UltraGreen.ai Shares Fall 15.9% as FY2026 Revenue Outlook Weakens
UltraGreen.ai shares closed down 15.9% after it forecast FY2026 revenue below guidance, as US competition and pricing pressure cloud growth.
UltraGreen.ai’s revenue growth has yet to shield its shares from pressure in its core US business. The medtech platform’s stock fell 15.9% on Thursday, Oct 29, after it said FY2026 revenue would come in below its earlier forecast. The company also expects the impact to extend into FY2027, leaving investors to weigh fast recent sales growth against a weaker outlook and pressure on pricing.
The shares opened at US$0.51, down from the previous close of US$0.565. At 9.08 am, they were trading at US$0.54, with about 355,500 shares changing hands at a cumulative value of US$184,405. The price later fell to US$0.505 by 2.48 pm before ending the day at US$0.475, a decline of US$0.09.
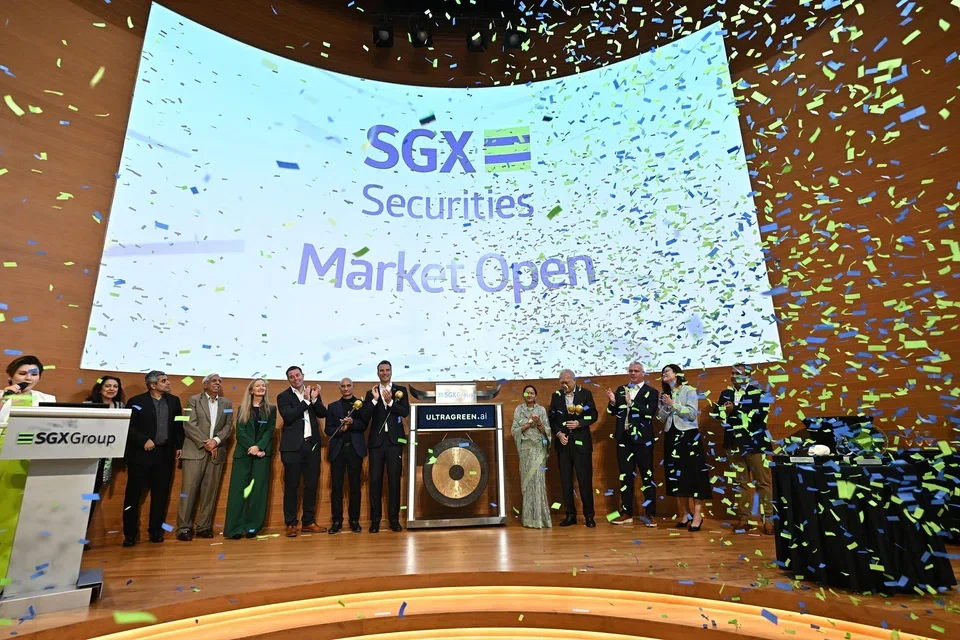
UltraGreen.ai listed on the Singapore Exchange’s mainboard in December 2025 at US$1.45. Thursday’s close was well below that listing price. The comparison gives a sense of the scale of the share-price move since listing, though it doesn’t explain the company’s future performance.
Revenue growth meets a lower forecast
The company’s third-quarter revenue rose 43.9 per cent to US$44.6 million, from US$31 million in the same period a year earlier. That increase points to substantial year-on-year expansion, but the business update shifted attention to what lies ahead: UltraGreen.ai expects FY2026 revenue to fall short of its previous guidance of US$175 million to US$185 million.

The company did not provide a revised revenue range in the details reported. That leaves the size of the expected shortfall unclear. The warning that its effects could continue into FY2027 also widens the period investors must assess: the challenge is not presented as a one-quarter disruption, and the available figures do not yet show how much of the growth slowdown may persist.
Quarterly revenue and full-year expectations measure different things. A strong increase against the prior-year quarter can coexist with a weaker full-year outlook when conditions change within the business or the company’s expectations for later periods shift. For UltraGreen.ai, the reported figures therefore show both momentum in Q3 and growing uncertainty around its ability to meet its earlier annual forecast.
Competition puts pressure on the core business
The company linked the reduced outlook to increased uncertainty in the US operating environment and the entry of competing indocyanine green (ICG) products. The new competition has brought pricing pressure and changes in customer purchasing patterns. Those shifts matter because they can affect revenue per sale as well as the volume and timing of purchases.
DBS Research said UltraGreen.ai faces pressure in its core ICG business in the US. Growth from outpatient consultations has not yet provided a meaningful earnings offset, the analysts said. That distinction is central: expansion into a new setting may add activity, but it needs to contribute enough to earnings to counter pressure in the established business.
UltraGreen.ai has relaunched generic ICG alongside its branded IC-Green and has increased engagement with distributors. It is also reviewing costs to protect profitability. These steps address different parts of the challenge: a generic product may help the company compete for customers, distributor engagement may support reach, and cost changes may help limit the effect on profit.
There are trade-offs. DBS Research cautioned that a greater share of lower-priced generic sales could dilute average selling prices and margins. Retaining customers through lower prices could help defend sales volumes, but the revenue and profit generated per unit may be weaker. The source figures do not quantify that potential effect, so the balance between customer retention and profitability remains an important unknown.
What would clarify the outlook
Camera sales offer another possible source of growth, but their contribution depends on clinics adopting the products and on an effective rollout, DBS Research said. That makes execution and customer uptake important alongside product availability. The report does not provide figures for clinic adoption or camera revenue, so the scale and timing of any contribution cannot yet be assessed from the reported information.
The research firm sees limited scope for a share-price re-rating until there is clearer evidence that core pricing and market share can hold up, or that newer outpatient applications can make a meaningful contribution to earnings. That assessment highlights two tests for the company: whether it can defend its position in US ICG sales, and whether newer uses can become a material source of profit.
For shareholders, Thursday’s fall reflects the gap between Q3 growth and the weaker full-year outlook, with uncertainty extending into FY2027. Customers and distributors may see more choice as competing products enter the market, while clinics’ purchasing decisions will influence adoption of UltraGreen.ai’s cameras. The next useful evidence will be the company’s updated revenue expectations and clearer signs of how pricing, customer demand, costs and outpatient growth are shaping its results.


