Dyed Diesel Relief FAQs Clarify Tax Reporting, Records and State Limits
The relief runs through year-end, easing federal dyed diesel reporting and penalty exposure while leaving state fuel rules and other taxes intact.
The federal relief for dyed diesel used on highways changes the tax and paperwork treatment of fuel through the end of 2026. FAQs posted by the IRS on Oct. 23 clarify that sellers, distributors, purchasers and end users generally need not document or report covered transactions during the relief period. The guidance also leaves several boundaries in place: state fuel requirements remain separate, other federal taxes still apply, and the agency is considering how to handle red dye left in vehicle tanks after the relief ends.
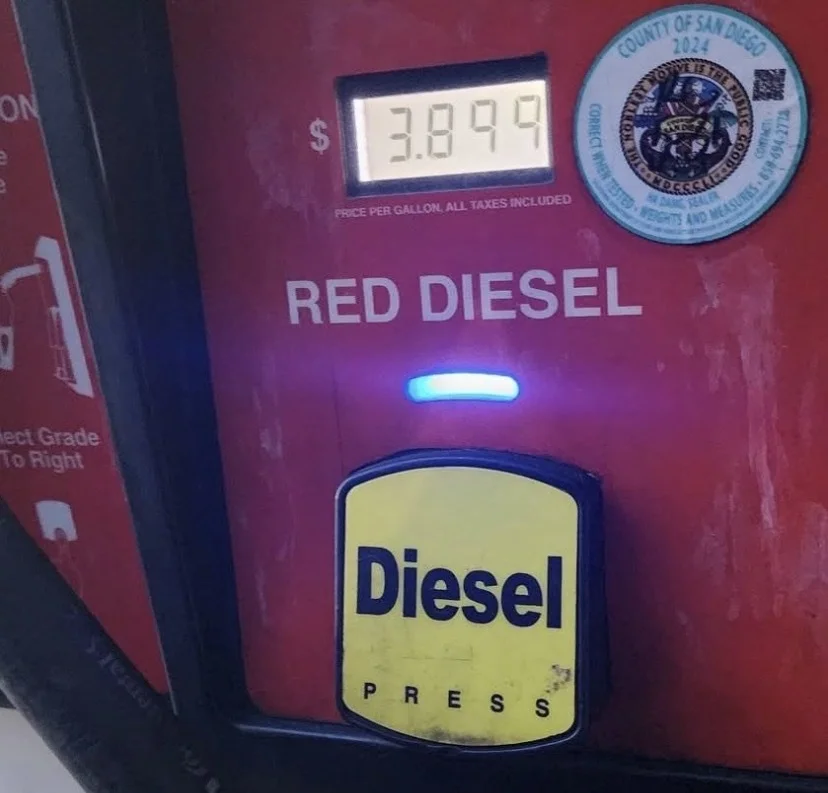
The IRS announced the relief on Oct. 14. It suspends federal penalties when dyed diesel is sold for highway use or used on U.S. highways through year-end, and defers federal taxes on the fuel without penalties or interest during that period. The FAQs give businesses and fuel users practical direction on how those terms affect records, tax returns and responsibility for fuel sold into the market.

Records and returns during the relief period
Under ordinary rules, dyed diesel is generally untaxed because it is intended for exempt uses such as farming. A federal excise tax can apply when the fuel is sold for highway use or powers a vehicle on a highway. Usually, the retail seller is liable; if the fuel was not bought at retail, the vehicle operator may be responsible. That can include fuel drawn from a farm storage tank.

For covered transactions during the relief period, the IRS says taxpayers aren’t required to create or keep records documenting dyed diesel distribution, sales or purchases. It also won’t challenge a failure to maintain records solely to establish liability for taxable uses of the fuel during the period. Businesses won’t have to reconstruct those records later.

That relief is limited. Records required independently for another tax, or to support an exemption, credit or refund claim, must still be kept. The recordkeeping relief also doesn’t cover other purposes outside the specified dyed diesel excise tax, or taxable uses after the relief period ends. Businesses with recordkeeping duties that overlap multiple tax matters will need to distinguish those obligations from the temporary relief.

The same boundary applies to Form 720. A taxpayer who normally files the return doesn’t have to report covered dyed diesel distributed, sold or purchased during the relief period, even if the return comes due later. That includes the fourth-quarter return, generally due Jan. 31 of the following year. If a business must file Form 720 for other taxes, it must still file and report those liabilities; the IRS says it won’t challenge omission of the covered dyed diesel liability.
Taxpayers who don’t normally file Form 720 also don’t have to begin filing solely to report covered sales. Nor will they have to report those sales after the relief period. The agency says the relief creates no new obligations for distributors, retailers, purchasers or end users, while requirements for other federal taxes remain in force.
Fuel types, state rules and liability
The relief addresses federal excise tax on dyed diesel only. It doesn’t change state fuel taxes or state requirements for dyed fuel, so interstate operators may encounter different rules as they cross state lines. The IRS directs taxpayers to state authorities for details. The temporary federal treatment therefore doesn’t establish a uniform rule for every part of a trip.

Clear diesel and dyed kerosene are outside the relief, and their federal tax treatment is unchanged. Dyed biodiesel mixtures are covered, however. The distinction matters for fuel suppliers and fleet operators handling multiple products: the temporary relief follows the eligible dyed diesel category rather than applying broadly to diesel or other fuels.
For the limited purpose of this relief, a seller of dyed diesel during the covered period is presumed not to know, and not to have reason to know, that the fuel will be used in a diesel-powered highway vehicle. The IRS says this prevents a seller or distributor from becoming liable for the dyed diesel excise tax merely because an end user ultimately takes the fuel on-road.
A separate charge may still be relevant. The $0.001-per-gallon Leaking Underground Storage Tank tax generally applies when dyed diesel leaves a terminal. If that tax has already been imposed, it isn’t charged again when the fuel is later sold for highway use or used on a highway.
What changes when the relief ends
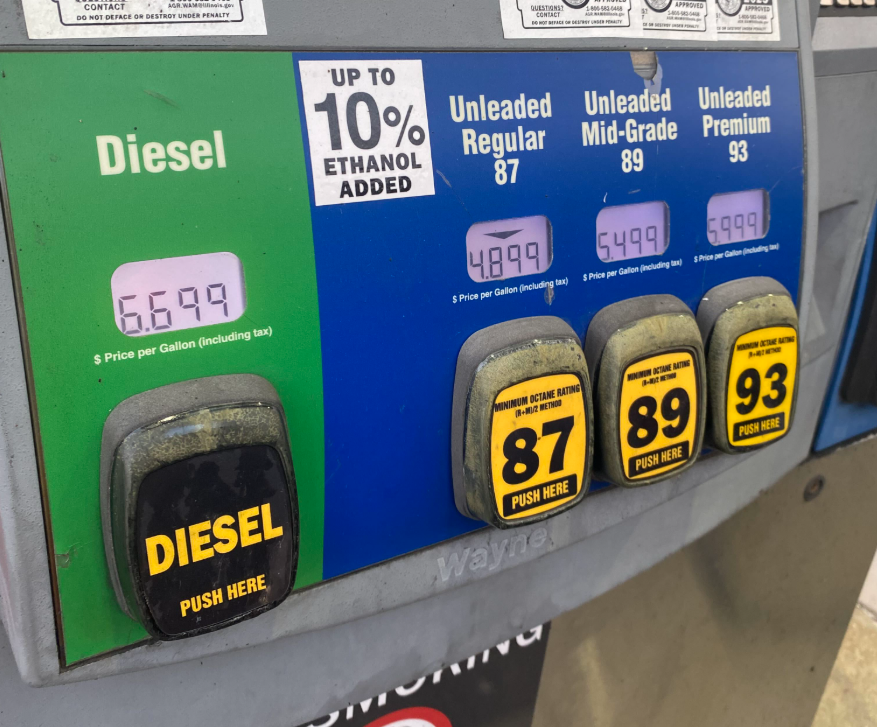
Dyed diesel is colored red to identify it as fuel intended for off-road uses such as agriculture, construction or heating. Clear diesel, by comparison, is federally taxed at 24.4 cents a gallon. The temporary allowance makes dyed fuel available for highway use through the end of the year, but the source doesn’t describe a permanent change to the usual distinction between the two products.
During the relief period, distributors and sellers aren’t expected to keep the required “nontaxable use only” notices in place. Those notices must be restored when the period ends. The IRS is also considering a grace period or other steps for residual red dye remaining in tanks, with further guidance to come. That unresolved point is relevant to operators whose equipment may still contain dyed fuel as the temporary window closes.
For now, the practical framework is specific: covered federal dyed diesel taxes receive temporary relief, associated records and reporting are relaxed, and sellers receive limited protection concerning eventual highway use. Other tax duties, state requirements and obligations tied to post-relief use remain. The next clarification to watch is how the IRS handles fuel and dye remaining in tanks after year-end.


